Essential or Optional? Understanding the Difference Between Your Insurance Policies and Their Impact on Your Finances
Essential or Optional? Understanding the Difference Between Your Insurance Policies and Their Impact on Your Finances
Insurance can often feel like a maze of terms, cover levels and fine print. Some policies are required by law, while others are entirely optional – yet all can have a major impact on your financial wellbeing when things go wrong. Knowing which policies are essential and which are simply advisable helps you make informed choices and avoid costly surprises.
The Mandatory Policies – What You Can’t Go Without
In the UK, only a few types of insurance are legally required, but they are crucial.
- Car insurance (third-party cover) – If you drive or own a vehicle, you must have at least third-party insurance. It covers damage or injury you cause to others or their property, but not your own vehicle. Driving without it can lead to fines, penalty points, or even disqualification.
- Employers’ liability insurance – If you employ anyone, even part-time or temporary staff, you are legally required to have employers’ liability insurance. It protects you if an employee is injured or becomes ill as a result of their work.
- Buildings insurance (for mortgage holders) – While not a legal requirement, most mortgage lenders insist that you have buildings insurance to protect the structure of your home against fire, flood or other damage.
These policies are non-negotiable. Without them, you risk not only legal penalties but also severe financial consequences if something goes wrong.
The Key Optional Policies – Your Financial Safety Net
Beyond the mandatory ones, there are several types of insurance that, while optional, can provide vital protection for your finances and peace of mind.
- Contents insurance – Covers your belongings against theft, fire, or accidental damage. It often includes personal liability cover, which protects you if you accidentally cause damage to someone else’s property.
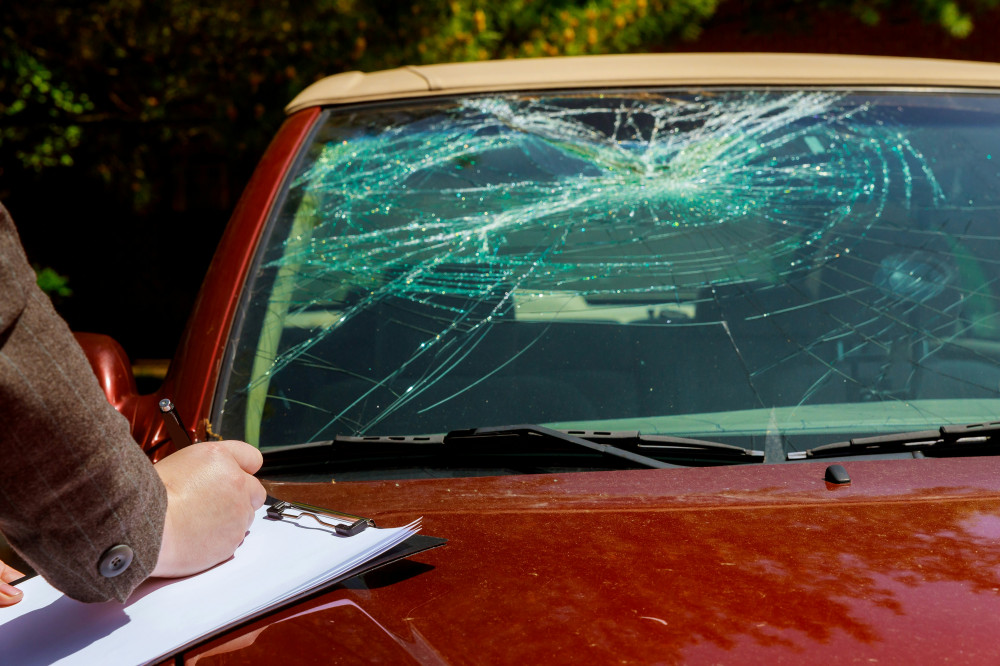
- Comprehensive car insurance – Goes beyond the legal minimum by covering damage to your own vehicle, even if an accident is your fault. It can also include extras like windscreen cover or courtesy cars.
- Travel insurance – Covers medical emergencies, cancellations, and lost luggage when travelling abroad. Without it, you could face huge medical bills if you fall ill overseas.
- Life insurance – Provides financial support to your family if you die. It’s especially important if you have dependants or a mortgage.
- Income protection or critical illness cover – Offers a safety net if you’re unable to work due to illness or injury. It can help you keep up with bills and living costs during difficult times.
- Pet insurance – Veterinary care can be expensive, and pet insurance can help cover unexpected costs if your pet becomes ill or injured.
Choosing the right mix of optional policies depends on your lifestyle, responsibilities and how much financial risk you’re willing to carry yourself.
The Cost of Being Insured – and the Cost of Not Being
Insurance premiums can feel like a burden, but they are essentially a way of spreading risk. You pay a predictable amount to avoid potentially devastating expenses later.
A burst pipe, a stolen car, or a cancelled holiday can all lead to significant costs. Without insurance, you might have to dip into savings or take on debt to recover. With the right cover, those same events become manageable inconveniences rather than financial disasters.
That said, it’s worth reviewing your policies regularly. You may be paying for cover you no longer need, or missing out on protection that’s become relevant as your circumstances change.
Læs også:
How to Get a Clear Overview of Your Insurance
- List all your current policies – Include those you hold personally and any provided through your employer or bank.
- Check what’s covered – Understand the limits, exclusions and excesses. Many people are surprised by what their policy doesn’t include.
- Compare providers – Use comparison websites or speak to brokers. Prices and terms can vary widely for similar cover.
- Update as your life changes – Moving house, starting a family or changing jobs can all affect your insurance needs.
- Review your excess – A higher excess can lower your premium, but make sure you could afford to pay it if you needed to claim.
Insurance as Part of a Healthy Financial Plan
Having the right insurance isn’t just about peace of mind – it’s a cornerstone of sound financial planning. It protects you from unexpected costs that could otherwise derail your budget or long-term goals.
Think of insurance as an investment in stability. You hope never to need it, but when you do, it can mean the difference between a temporary setback and a financial crisis.
Conclusion: Security Comes from Understanding
The difference between essential and optional insurance isn’t just about legal requirements – it’s about taking responsibility for your financial wellbeing. The mandatory policies form the foundation, but the optional ones can be what keeps you afloat when life takes an unexpected turn.
By understanding what you’re paying for and why, you can build an insurance portfolio that fits your life – not too much, not too little, but just enough to give you confidence and peace of mind.
Læs også: